
Budget, banks and the search for FX direction
Market overview
Global currency markets are heading into a potentially decisive session, with today's UK Budget taking centre stage alongside major central bank decisions, shifting interest rate expectations and changing investor sentiment. The dollar continues to regain momentum, sterling is trading near multi-month highs against the euro, and the single currency remains under pressure. Elevated energy prices, persistent inflation and geopolitical tensions are adding to market caution, although renewed optimism surrounding artificial intelligence has helped restore some confidence in risk assets.
Attention now turns to a packed economic calendar, with fiscal announcements and upcoming decisions from the Federal Reserve and European Central Bank capable of reshaping currency valuations. Investors are particularly focused on whether policymakers reinforce expectations of further monetary tightening or introduce fresh uncertainty. With positioning already favouring the dollar and sterling over the euro, upcoming announcements could determine whether recent trends extend or markets experience a sharp reversal.
GBP: Sterling faces a crucial Budget test
Sterling enters today's UK Budget close to its strongest level against the euro in 17 months, with GBP/EUR trading around 1.1943. Expectations for a relatively restrained fiscal announcement have supported confidence in UK assets, alongside growing anticipation of further Bank of England tightening. However, with markets already positioned for a largely uneventful Budget, unexpected policy measures could leave the pound vulnerable.
Chancellor John Healey's fiscal plans and the accompanying OBR forecasts will be closely scrutinised, particularly regarding borrowing requirements, gilt yields and the government's remaining fiscal headroom. A disciplined Budget, supported by encouraging economic projections, could reinforce sterling's recent gains and bring GBP/EUR closer to 1.20. Conversely, unfunded spending commitments or weaker fiscal forecasts could unsettle bond markets and reverse some of the pound's recent strength.
USD: Dollar momentum builds ahead of the Fed
The dollar extended its winning streak to three sessions yesterday, with the Dollar Index approaching the important 102.50 resistance level. The Federal Reserve is widely expected to leave interest rates unchanged this evening, making Chair Kevin Warsh's commentary the principal focus. Markets continue to anticipate another increase in December, supported by persistent inflationary pressures, higher energy costs and ongoing geopolitical uncertainty.
With no updated economic projections accompanying today's decision, investors will look for clues in the Fed's statement, voting split and subsequent press conference. A firm commitment to containing inflation could reinforce dollar demand, particularly if upcoming US growth figures and technology earnings ease concerns surrounding AI investment. A sustained move above 102.50 would bring 103.00 into focus, while the broader outlook remains supportive of further dollar strength.
EUR: Euro struggles as economic and fiscal pressures mount
The euro remains on the defensive, with EUR/USD slipping below 1.12 as the recent recovery loses momentum. The pair is approaching significant technical support around 1.11, where a sustained break could open the door to further losses. Weak economic indicators, rising natural gas prices and continued uncertainty surrounding French public finances are weighing on confidence in the single currency.
Tomorrow's ECB announcement presents another challenge, with policymakers balancing inflation risks against mounting pressure in European sovereign debt markets. A softer policy stance could widen the interest rate differential with the US and weaken the euro further, while maintaining a restrictive approach risks prolonging financial strains. With the dollar retaining its underlying strength, the near-term outlook for EUR/USD remains cautious, while EUR/GBP could extend its decline towards 0.8315.
Monfor 48-hour FX forecast: Key levels to watch
With several major market-moving announcements approaching, currency volatility could increase as investors respond to fresh economic and policy signals. Our indicative trading ranges for the next 48 hours reflect the potential for further dollar strength, relative sterling resilience and continued pressure on the euro.
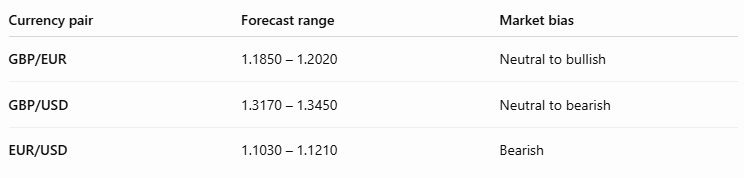
Sterling could test the 1.20 level against the euro if the Budget delivers fiscal reassurance, while a hawkish Federal Reserve may keep GBP/USD under pressure. Meanwhile, EUR/USD remains vulnerable to a break below 1.11, particularly if contrasting central bank signals reinforce demand for the dollar. These ranges are illustrative scenarios rather than guaranteed trading boundaries.
Looking ahead
UK Budget (today): Focus on fiscal discipline, OBR forecasts, gilt market reactions and any implications for Bank of England policy.
Federal Reserve (today): Interest rates are expected to remain unchanged, with attention on Kevin Warsh's guidance regarding a potential December increase.
US technology earnings (today): Results from Microsoft and Alphabet could influence broader risk sentiment and confidence in AI-related investment.
ECB meeting (Thursday): Markets will assess the central bank's policy outlook against persistent inflation and European fiscal concerns.
US Q3 GDP (Thursday): Stronger-than-expected growth could strengthen the case for further US monetary tightening and provide additional support for the dollar.